As a new calendar year begins, Fit and Proper reviews once again come into focus across Regulated Financial Institutions. Annual declarations, internal reviews and board attestations are familiar fixtures of the compliance cycle. These remain a key mechanism through which Regulated Financial Institutions demonstrate to the Monetary Authority of Singapore (MAS) that individuals performing regulated roles continue to meet suitability expectations.
The MAS’ Guidelines on Fit and Proper Criteria (FSG-G01) (the Guidelines) make clear that Fit and Proper is not designed to be a yearly administrative ritual. Regulated Financial Institutions must apply it as an ongoing assessment, proportionately, thoughtfully and with proper documentation. It is a core governance safeguard, one that underpins trust in the financial system and the people who operate within it.
As Regulated Financial Institutions prepare for 2026 governance, compliance and declaration cycles, this is an appropriate moment to revisit what Fit and Proper truly means in practice.
The MAS Fit and Proper Framework
Trust forms the fundamental basis for an effective and efficient financial services market.
Clients place their savings, investments, and long-term financial plans in the hands of institutions and professionals. They expect these parties to be competent, ethical, and to act in accordance with their fiduciary duties in the client’s best interests. Regulators, in turn, need confidence that such entities are led and staffed by individuals who meet those same standards, and can be trusted to make competent, sound decisions.
This is where the Fit and Proper standards play a central role towards safeguarding the interests of the end consumer, and of the hiring Regulated Financial Institution.
MAS sets the professional and ethical expectations for those operating within Singapore’s financial system. However, operators are responsible for incorporating these expectations into their initial and ongoing hiring and compliance policies. The objective is not only to address misconduct when it occurs, but to establish a clear baseline of suitability, competence, and integrity for those performing regulated roles. This reduces the risk of misconduct and governance failures over time.
Understanding FSG-G01: The Regulatory Framework
Notably, the Guidelines apply broadly across the multitude of regulated activities here in Singapore. This includes the Capital Markets, Financial Advisory, Insurance and Payment Services sectors, as well as entities separately regulated under the Financial Services and Markets Act.
The Guidelines require every relevant person to satisfy the Fit and Proper standards. At the same time, MAS recognises that different roles carry different responsibilities. It requires subjective assessments to be calibrated to the nature, scope, and risk profile of the role in question.
The Guidelines are built on three core pillars:
1. Honesty, integrity and reputation – The individual must be of good character and conduct themselves with integrity
2. Competence and capability – The individual must possess the qualifications, skills and experience necessary for their role
3. Financial soundness – The individual must manage their financial affairs prudently
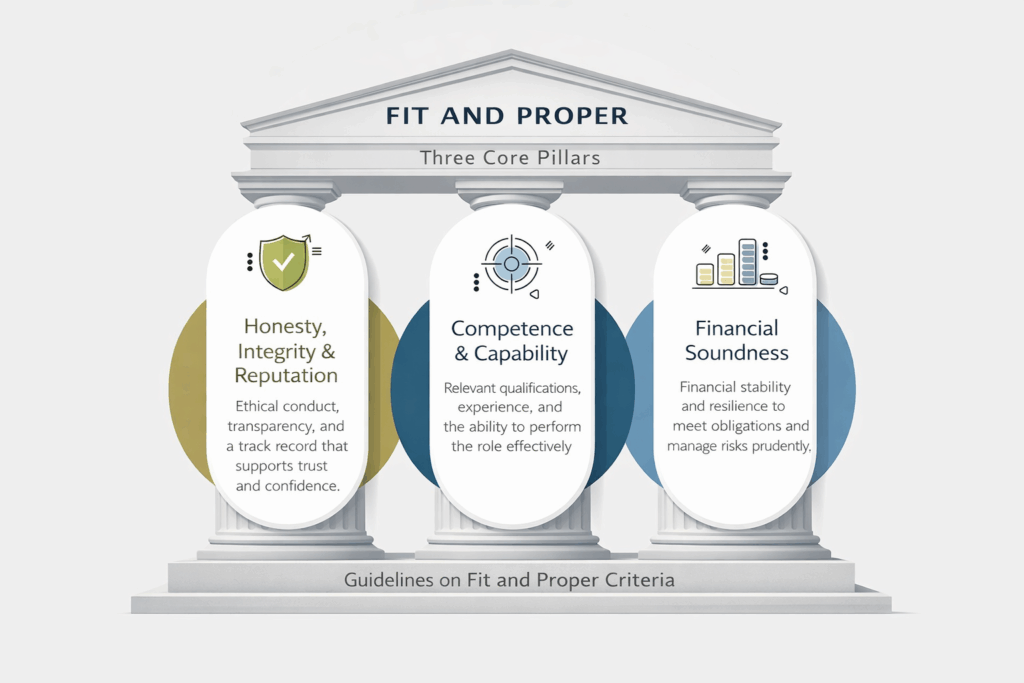
Overall. these pillars apply consistently across sectors. However, the depth and manner of assessment will vary depending on the role and its associated risks. On paper, the framework is simple. In practice, it requires a more nuanced evaluation that requires detailed deliberation.
Who Is Subject to Fit and Proper Assessments
The Guidelines and their applicability do not stop at the boardroom door.
Indeed, the requirements extend well beyond just board members and chief executives. Under the Guidelines, they apply to a wide range of individuals, including:
- CEOs, directors, controllers and senior management
- representatives and other regulated individuals
- employees and officers of payment service providers
- staff of capital markets intermediaries
- individuals involved in digital token service providers
In other words, if a role can affect clients, markets or the handling of monies, the Guidelines will apply to that role.
This wide application addresses the risk that certain functions may extend beyond leadership roles. As a result, it applies to anyone whose decisions, systems, or customer interactions can affect market integrity, customer interests, or institutional soundness.
For Regulated Financial Institutions, this means Fit and Proper implementation and monitoring frameworks must be practical, yet comprehensive enough to apply across the organisation, not just at senior levels.
Fit and Proper in Practice: Beyond a Tick-Box Exercise
Contextual and Proportionate Assessments
One of the most frequently misunderstood aspects of the Guidelines is how Regulated Financial Institutions treat past conduct.
The Guidelines are explicit that failing to meet one criterion does not automatically result in refusal, revocation or regulatory action. Regulated Financial Institutions are expected to consider factors such as the seriousness of the issue, its relevance to the role, and the time that has passed.
The MAS’ Parliamentary Reply on Fit and Proper assessments and career entry reinforced this position. MAS clarified that past conduct, including matters raised publicly, does not in itself render an individual unfit for a career in the financial services industry. What matters is whether the individual is suitable to perform the specific role responsibly and competently, once viewed in the context of their role and function.
For compliance teams, this therefore underscores the importance of reasoned decision-making supported by documentation, rather than rigid or formulaic assessments.
Implications for Hiring, Onboarding and Role Changes
Typically, Fit and Proper considerations arise at multiple points in an individual’s lifecycle within a Regulated Financial Institution These include initial hiring, onboarding into regulated roles, promotions, changes in responsibilities and transitions across business lines.
While Human Resources (HR) teams often lead recruitment processes, compliance oversight also plays a critical role. It ensures Fit and Proper assessments are conducted consistently and aligned with regulatory expectations. Clear communication between HR, line management and compliance is essential to ensure that assessments are conducted consistently and aligned with regulatory expectations.
For Singapore Fund Management Companies, the Guidelines on Licensing and Conduct of Business for Fund Management Companies (SFA 04-G05) also set out specific expectations on the conduct of background and due diligence checks as part of the Fit and Proper assessments. Paragraph 3.6 of SFA04-G05 states that Singapore Fund Management Companies should perform adequate due diligence on prospective representatives and employees. This includes reference checks with previous employers to verify credentials, work experience, and any disciplinary record. Where individuals are hired based on an asserted investment track record or strategy, such entities are also expected to validate these track records before appointment, rather than relying solely on the individual’s own representations.
These expectations underscore the importance of close coordination between HR, senior management and compliance functions. Without a clear process, ownership and communication, institutions may apply Fit and Proper assessments inconsistently or in a fragmented manner.
From a governance perspective, Fit and Proper requirements are best integrated into these processes early, rather than introduced at the end as a final hurdle.
Fit and Proper Declarations and Ongoing Obligations
Declarations as Part of Regulatory and Internal Governance
In practice, Fit and Proper declarations are one of the main tools that Regulated Financial Institutions use to operationalise the Guidelines. Most Regulated Financial Institutions require staff to submit a Fit and Proper declaration upon:
- commencement of employment,
- to reaffirm their status annually, and
- to notify compliance or management when there are any changes in circumstances.
These declarations support regulatory notifications, internal governance and audit readiness. More importantly, they create a structured moment for Regulated Financial Institutions to consider whether anything relevant has changed. They create a structured moment for Regulated Financial Institutions to consider whether anything relevant has changed.
Annual Review as a Governance Practice
Although MAS does not prescribe a single universal annual declaration format across all licence types, the industry widely recognises annual reaffirmations for Board Members, CEOs, appointed representatives, and key appointment holders as good governance practice. This ensures information on relevant personnel remains updated at all times. This in turn allows for the Regulated Financial Institution to easily demonstrate oversight and governance with the supporting documentary evidence.
As Regulated Financial Institutions approach the new year, these annual reviews therefore provide a natural opportunity to reassess whether existing processes remain fit for purpose. This depends on the entity’s size, complexity, and specific personnel arrangements.
Additionally, while frequency may be a contentious point, the market is gradually moving toward more regular background checks. These serve as independent, corroborative evidence that regulated personnel remain “Fit and Proper”.
Common Compliance Challenges
Despite clear regulatory guidance, familiar challenges continue to arise across the industry:
- declarations treated as routine formalities rather than substantive reviews
- inconsistent assessment standards across business units
- inadequate documentation to support regulatory notifications
- over-reliance on criminal record checks without contextual analysis
- unclear escalation processes when disclosures are made
Addressing these issues requires more than updated forms. Instead, institutions need a framework that they understand, apply consistently and support through effective governance.
Building a Robust Fit and Proper Framework for 2026
In practice, a workable framework does not need to be complex. However, it does need to be deliberate.
Key elements should include:
- clear internal policies aligned with regulatory expectations
- structured assessment and escalation processes
- documentation standards that can withstand regulatory scrutiny
- integration with hiring, onboarding and annual declaration processes
- training for HR, compliance and senior management
The Guidelines and their impositions should be treated as a living obligation, embedded into governance rather than confined to periodic compliance checklists.
Conclusion: What This Means for Your Institution
Institutions should not treat the Fit and Proper requirements as a procedural exercise to complete once a year. It is a governance obligation that reflects a Regulated Financial Institution’s commitment to integrity, competence and accountability.
MAS expects assessments to be fair, reasoned and defensible, taking into account both regulatory standards and real-world context. As regulatory expectations continue to evolve across capital markets and payment services, institutions must ensure that their fit and proper processes evolve accordingly. Doing so protects regulatory standing, organisational resilience and trust.
How Curia Regis Can Support
Curia Regis works with Regulated Financial Institutions in Singapore across the capital markets space as well as payment services, including at the intersection between the two.
Our work supports institutions in translating MAS’ Fit and Proper expectations into practical, defensible compliance frameworks, including:
- Reviewing fit and proper policies and procedures
- Supporting assessments for senior management and representatives
- Aligning internal practices with MAS Guidelines and regulatory requirements
- Conducting governance readiness reviews
- Advising on complex or sensitive fit and proper assessments where judgment and documentation are critical
Ready to strengthen your Fit and Proper framework for 2026? Contact us to discuss how we can support your institution’s compliance readiness.
You can reach us here or email admin@curiaregis.com to get in touch.


